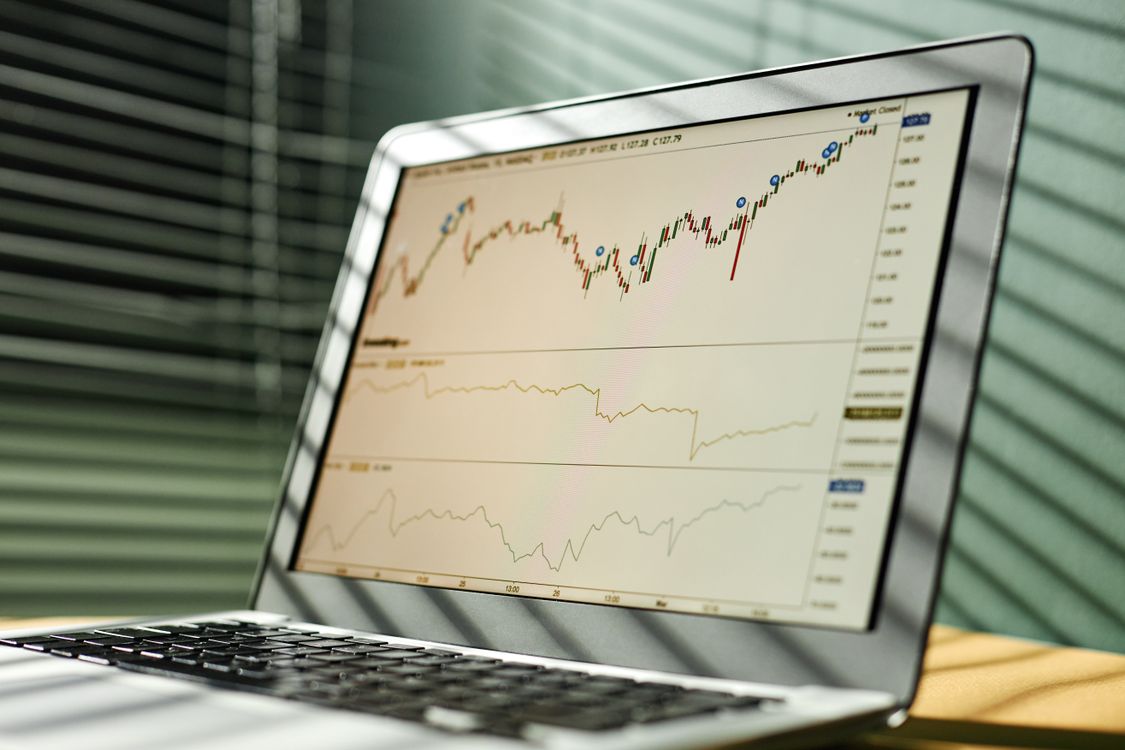
Friday is ending with a strange mood on Wall Street. The headline numbers look cheerful, the kind of green screen that makes your 401(k) statement feel a little friendlier. Around noon in New York, the Dow was up about 0.7%, with the S&P 500 and Nasdaq each climbing roughly 0.5 to 0.6%, according to Investor’s Business Daily. But zoom out and the week tells a different story, and that tension is worth sitting with for a minute.
Here is the split. The S&P 500 and Nasdaq are on pace for weekly gains (they entered Friday up 0.7% and 1.6% for the week, respectively), but the Dow is on pace for its fourth straight weekly loss, according to Investopedia. So the same week can feel like a win or a loss depending on which index your retirement money follows. That is not a market speaking with one voice. It is a market arguing with itself.
The argument is about oil and bonds, mostly. Oil pulled back on Friday, which gave stocks some breathing room. West Texas Intermediate crude slipped about 0.8% to below $94 a barrel, while Brent crude fell to around $106, after Reuters reported that the U.S. and Iran had discussed a deal to reopen the Strait of Hormuz. Any whiff of calm around shipping lanes takes a little heat out of fuel prices, and lower fuel prices take a little heat out of inflation fears.
But the bond market is not buying the calm, not fully. The 10-year Treasury yield sat near 5.17% to 5.21%, up about 21 basis points for the week, after hitting its highest intraday level since 2007 on Thursday, per Investopedia. When the benchmark for mortgages and corporate borrowing is at a nearly two-decade high, stocks are effectively climbing a wall of higher interest rates.
Individual movers told the day’s story in miniature. Super Micro Computer was a top IBD 50 performer, rising nearly 3%, with Veeva Systems, Snowflake, WisdomTree and Aura Minerals each up 1% or more. On the downside, Cloudflare fell more than 3% and Rubrik gave back nearly 2%.
One fun subplot: Nvidia. Late Thursday, SpaceX CEO Elon Musk posted on X that the company’s xAI Memphis data center already houses several of Nvidia’s Hopper and Blackwell chips, with another 220,000 Blackwell chips expected by November, and possibly another 220,000 GB300 chips by late December, as part of a plan to equip the site with a million chips this year. Nvidia shares edged just 0.1% lower but held above their 21-day moving average. When a CEO casually announces hundreds of thousands of chips incoming, you can see why the AI trade refuses to die.
Bitcoin slid to around $84,000, and small caps sat out the party, with the Russell 2000 down about 0.2% at midday.
What to watch next: the week closes today, and next week brings the heavy artillery, the September jobs report on October 2 and September inflation figures on October 14. With the Fed having just raised rates in September and another hike priced at roughly 64% for October, every data point is now a Fed data point. Enjoy the green afternoon, but keep an eye on the bond market. It has been telling the truth all week.